They are drawn by surge in demand and cut in global production capacity
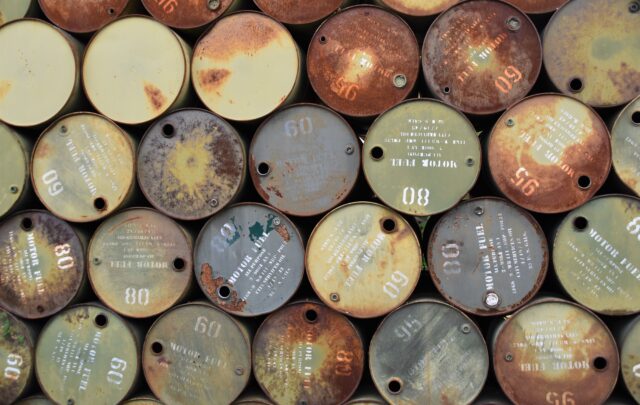
WITH heavy investment fund buying driving oil prices up 27 per cent this year to a 21-year high, opinion is divided on whether large funds are buying on the basis of solid market fundamentals or creating a bubble, the Financial Times said.
Oil has become the market of choice for speculators in recent months with a niche group of unknown investors holding a significant portion of the total outstanding crude-related energy contracts on the New York Mercantile Exchange.
That volume is equivalent to an underlying one billion barrels of crude oil and petroleum products, or about 4 1/2 months worth of global consumption.
‘There is no doubt that there is a speculative bubble that has created a big premium in the price, which should be closer to US$30 to US$32 a barrel based on the current supply and demand trends,’ Mike Rothman, chief energy strategist at Merrill Lynch told the FT. He is predicting a sharp increase in global crude inventory levels over the next month. ‘Speculative interest in oil is at unprecedented levels.’
Speculators have been attracted to the energy futures because of the surge in oil demand as the global economy has grown at its fastest pace in several years and a reduction in global production capacity, tightening the oil market.
The loss of price control from producers to the futures markets since 1983 has been a sore point with members of the Organisation of Petroleum Exporting Countries, who do not use these markets.
Despite the increasing fund presence, there is a school of thought that the key measurement to determine whether speculators are influencing the higher price is the net position between those who buy on the long side – the camp that expects prices to continue to rise – and those who buy on the short side, investors who expect prices to fall.
Kevin Norrish, energy analyst at Barclays Capital, said this net position had fallen from its peak in March, meaning that fewer people now think prices will keep rising. Despite that, crude prices have risen US$8 since then.
However, the current level is still double that of last year – a net position that was considered a record at the time.
‘If the net position had continued to grow with the increase in speculative interest in crude oil then that would reflect a bubble, but we are not seeing that. The buying is based on market fundamentals of strong demand and concerns about security of supply,’ Mr Norrish told the FT.
Yesterday, US oil prices held strong above US$41 as traders expected a rise in US petroleum inventories. According to a Reuters report, US light crude futures were up two cents at US$41.16 a barrel, after a 58-cent fall on Tuesday. London Brent crude rose six cents to US$37.50 a barrel in the early afternoon.
Prices have failed to respond even to leading Opec producer Saudi Arabia’s promise to raise production sharply in June and pump at full capacity if necessary.
Fears are the funds will stay long in oil, and wait to see firm evidence of inventory builds in key consumer economies before relaxing their bet on continued oil strength.
Comments
Welcome to the new Resillience commenting system!
We have moved from the former Disqus commenting system to a new system as of September 10, 2026.
We made this change because of privacy concerns regarding Disqus. It's also part of a set of changes to bring more services to the Resilience community under a single login: commenting, (coming September 2026), and online courses (coming 2027). Unfortunately, your old Disqus comments may not reliably link to your account in this new system. Please contact us if you have any questions or concerns.